Mortgage Strategy Review
Key Takeaways
- Review your property finance with a broker every six to twelve months.
- Arrange an earlier mortgage strategy review when your income, employment, family circumstances or investing goals change.
- Speak with a broker before buying, refinancing, fixing a rate or accessing equity.
- A thorough investment loan review should assess your loan structure, repayments, features, equity position, credit file and future plans.
- A lower advertised rate is not automatically a better outcome once fees, features and structural consequences are considered.
- PropertyChat.ai provides general education based on more than 20 years of property investing, mortgage and renovation knowledge. It does not provide current market data, calculate returns or replace personalised financial advice.
A mortgage strategy review should happen every six to twelve months, not only when interest rates move or a lender advertises a tempting offer. For a property investor, finance is part of the investment strategy. Your loans need to support your cash flow, borrowing position and next planned move.
The loan that suited you two years ago may no longer suit your income, family or portfolio. Waiting until you want to buy, renovate or refinance can expose problems when there is little time to solve them. Regular reviews help you identify those issues earlier and take informed action with a qualified broker.
How often should property investors review their mortgage?
For most active Australian property investors, the practical answer is every six to twelve months.
A six-month cycle can suit investors who are actively expanding a portfolio, preparing for a renovation or experiencing changing income. An annual mortgage review may be enough for an investor whose financial position and plans are relatively stable.
If you are wondering how often to review mortgage arrangements, remember that the calendar is only a starting point. You should not wait for your next scheduled appointment if something important changes.
| Investor situation | Suggested review timing |
| Stable income and no immediate purchase plans | Every 12 months |
| Building a portfolio or preparing to buy | Every 6 months |
| Fixed-rate period approaching its end | Several months before expiry |
| Planning to access equity | Before committing to the project |
| Income, employment or family situation changes | As soon as practical |
| Considering refinancing | Before submitting applications |
| Major change to investment goals | Immediately |
The purpose is not to refinance twice a year. It is to confirm that your existing lending still supports the direction in which you are heading.
A regular review can also help you prepare for a broader property portfolio review, particularly when your next goal depends on borrowing capacity, equity access or changes to your cash flow.
Why can an unchanged loan become a problem?
A loan can remain exactly the same while everything around it changes.
Lenders can change assessment methods, product features and servicing policies. Your income, expenses, debts and dependants can also change. Meanwhile, a property may gain equity, a fixed period may expire, or your next investment plan may require a different finance structure.
Imagine an established professional who owns a home and two investment properties. Her repayments are manageable, so she assumes the lending is fine. Twelve months later, she wants to purchase again. Only then does she discover that her current structure makes equity access more complicated and her recent credit enquiries need explanation.
The danger is not always an obviously expensive mortgage. Sometimes it is a loan that quietly restricts your next step or weakens your borrowing capacity for an investment property.
That is why experienced investors treat finance as an active part of portfolio management rather than administration completed at settlement.
What events should trigger an immediate investment loan review?
Contact your broker whenever your financial circumstances or goals shift significantly. The most common triggers include:
- receiving a pay rise or experiencing a reduction in income
- changing jobs, industries or employment arrangements
- starting or purchasing a business
- getting married, separating or combining finances
- planning for a baby or taking parental leave
- taking on car finance, personal debt or new credit cards
- preparing to buy another investment property
- planning a substantial renovation
- considering interest-only or principal and interest repayments
- approaching the end of a fixed-rate period
- selling a property within the portfolio
- wanting to release equity
- considering refinancing or debt consolidation
Timing matters. If you are planning parental leave, for example, speaking with a broker before the income change may provide more time to understand your options. That does not guarantee approval or a particular outcome, but it helps you avoid making major commitments without understanding how they may affect your lending position.
Similarly, if you are considering refinancing an investment property, arrange the review before submitting applications. This gives you and your broker time to compare costs, policies, loan features and possible structural consequences.
What should a property investor mortgage broker examine?
A useful review goes much deeper than asking whether another lender has a lower rate. A property investor mortgage broker should consider how each loan fits within your wider property strategy.
Your goals and likely next move
Your broker should first understand what you are trying to achieve. Are you buying within twelve months, renovating an existing property, improving cash flow or reducing debt before retirement?
Without that context, product comparisons can become disconnected from your actual property strategy.
Be ready to explain your immediate goal as well as the next one or two moves you may want to make. A loan that works for today’s purchase may create complications if it is not considered as part of a longer-term property portfolio loan strategy.
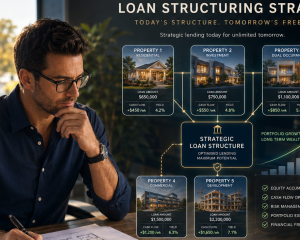
Your current investment property loan structure
The broker can examine loan purposes, repayment types, fixed and variable portions, offset accounts, redraw facilities and whether personal and investment debts are clearly separated.
Your investment property loan structure is particularly important when you own several properties. Poorly organised lending can create complexity, reduce flexibility and make record keeping more difficult. Tax consequences should always be checked with a qualified accountant or tax adviser.
For further general education, visit the PropertyChat.ai mortgage broker information hub and property investing resources.
Your repayments, interest rates and loan features
A review can compare your existing arrangements with alternatives available through the broker’s approved lender panel. The lowest advertised rate is not automatically the best choice.
An offset account, repayment flexibility, access to support and suitable lending policies may matter more than a small headline difference. Conversely, paying for features you never use can add unnecessary cost.
An interest rate review for a property investor should therefore consider the complete loan arrangement, not just the advertised percentage.
Your equity and loan-to-value position
A broker can help you understand the information a lender may require when you want to access equity. If refinancing pushes the loan-to-value ratio above a lender’s threshold, lenders mortgage insurance may apply.
Available equity is not the same as accessible equity. Approval still depends on the lender’s assessment, your ability to service the debt and its current policies.
If equity is intended to fund another purchase or renovation, discuss the proposed use of those funds before changing the loan structure.
Your credit profile and application history
Multiple applications and poorly timed credit enquiries can complicate future borrowing. A review gives your broker an opportunity to discuss your credit report, existing limits and the order in which potential applications might be considered.
This does not mean manipulating an application. It means presenting accurate information and avoiding unnecessary enquiries.
Your future borrowing capacity
A review should also consider how the current arrangement may affect future lending. This is particularly important if you are planning another purchase, changing employment or taking on additional debt.
Borrowing capacity is not fixed. It can vary between lenders and change as your income, expenses, liabilities and personal circumstances change. A broker cannot guarantee how much you will be able to borrow in the future, but they can help you understand the factors lenders may assess.
What questions should you ask during a mortgage strategy review?
A productive review should leave you with a clearer understanding of your current position and the decisions ahead. Consider asking:
- Does my current loan structure still support my next property goal?
- Am I paying for loan features I do not use?
- Could refinancing affect my future borrowing capacity?
- What costs would apply if I changed lenders?
- Would a new loan term increase the total interest paid?
- Is my personal and investment debt clearly separated?
- What information would a lender need if I wanted to access equity?
- How could a fixed-rate expiry affect my repayments?
- Should I speak with my accountant or solicitor before making a change?
- What should I prepare now if I plan to purchase it within the next twelve months?
These questions can help you move beyond a simple rate comparison and assess whether the loan supports your wider investment strategy.
Is refinancing an investment property always the best result?
No. A responsible review may conclude that you should keep your current loan.
Refinancing can potentially reduce interest costs, improve features or create a more suitable structure. It can also involve discharge fees, application costs, valuation expenses, government charges and possible lenders mortgage insurance. Extending a loan term may reduce monthly repayments while increasing total interest over time.
Before proceeding, ask for a clear comparison covering:
- all estimated switching costs
- the proposed repayment and loan term
- the features gained or lost
- the effect on each property and loan
- any fixed-rate break costs
- possible tax or accounting questions
- how the change supports your next move
Do not refinance simply because a cashback offer or introductory rate looks attractive. The right comparison is the overall position before and after the change.
You can also use the PropertyChat.ai refinance education chat to prepare questions before speaking with a licensed professional.
Mortgage broker vs bank: which relationship helps investors?
A bank generally discusses products available through that institution. A broker may compare options from the lenders on their panel, subject to your circumstances and eligibility.
However, access to more lenders is only part of the value. Property investors need someone who understands that one loan decision can affect the wider portfolio.
A transaction-focused broker may help arrange a loan and reconnect near the next application. A strategy-focused mortgage broker for property investors should maintain appropriate contact, understand your goals and encourage regular reviews.
Look for a broker who:
- has experience with property investors and multiple loans
- explains recommendations in plain English
- discusses risks, costs and trade-offs
- asks about future plans rather than only the current transaction
- is transparent about lender panels and remuneration
- works constructively with your accountant and solicitor
- does not pressure you into unnecessary refinancing
A good broker cannot guarantee approval, future borrowing capacity or investment performance. They can help you understand lending choices and prepare a more coherent finance plan.
How can you prepare for a productive annual mortgage review?
Preparation makes the conversation faster and more useful. Gather:
- recent loan statements
- income evidence
- a list of living expenses and other liabilities
- current credit card limits
- lease or rental information where relevant
- details of planned renovations or purchases
- your expected time frame
- questions about repayments, equity and flexibility
Then write down the next two moves you would ideally like to make. Even if those plans change, they give the broker a direction against which to assess your existing arrangements.
It may also help to prepare a simple mortgage review checklist covering your loan balances, interest rates, repayment types, fixed-rate expiry dates, offsets, redraw facilities and credit limits.
Use PropertyChat.ai to learn the terminology and develop questions before the appointment. The platform draws on Jane Slack-Smith’s more than 20 years of experience in property investing, mortgages and renovation. It offers general educational guidance, not current lender data, financial advice, personalised recommendations or return calculations.
Make a mortgage strategy review part of your annual plan
The best time to discover a finance problem is before you need the money.
Set a recurring reminder for every six to twelve months and book an earlier conversation whenever your circumstances or plans change. The outcome may be refinancing, restructuring, preparing documentation or simply confirming that the current arrangement remains suitable.
A regular review is not about chasing every new interest rate or changing lenders unnecessarily. It is about making sure your finance continues to support your cash flow, investment goals and wider property portfolio review.
Ready to take action? Ask PropertyChat.ai what questions to take to your broker, then book a mortgage strategy review with a qualified mortgage professional. One organised conversation now could help you avoid a rushed decision when your next property opportunity arrives.
Related PropertyChat.ai articles
- How Mortgage Brokers Help Property Investors Build a Smarter Loan Strategy
- Loan Structuring in Australia
- Does Changing Lenders Affect Your Future Property Investment Borrowing Capacity?
- Interest-Only Loan vs Principal and Interest: Australian Property Investor’s Guide
- Risks of Using Home Equity to Invest
- Mortgage Broker vs Direct Lender for Refinancing
This article is provided in line with the Brand Voice of PropertyChat and Your Property Success, emphasising trust, actionable advice, and long-term partnership in property finance.
Transcript
Mortgage Strategy Review: Are Your Loans Still Working for You?
0:00
Welcome to this explainer. Today we’re diving straight into something absolutely crucial for anyone holding property debt. Mortgage strategy reviews. We’re going to look at why
0:09
leaving your property finance on autopilot might literally be the biggest roadblock to building your wealth and how a regular review just changes the
0:17
whole game. So, picture this. You’ve got an established professional owns her own home plus a couple of investment properties. Her repayments feel totally
0:25
fine. So, naturally, she assumes her lending is good to go, right? Well, fast forward 12 months. She tries to buy her next place and bam, hits a total brick
0:34
wall. Turns out her loan structure made accessing her equity an absolute nightmare, severely weakening her borrowing position. Which begs the
0:41
question, is your loan quietly restricting your next step? You know, the biggest financial danger isn’t always some obviously expensive mortgage
0:49
rate. Sometimes the real danger is just doing absolutely nothing. In this explainer, we’re breaking it all down. We’ll look at the unchanged loan trap.
0:58
exactly when you need to trigger a review, why you need to look beyond the interest rate, whether refinancing is actually the right move, and finally,
1:05
how to prepare. All right, part one, the unchanged loan trap, or what we call the set and forget trap. There’s a great
1:13
saying, experienced investors treat finance as an active part of portfolio management rather than administration completed at settlement. And they really
1:22
do. You can’t just sign the papers and forget about it. Your loans are a living, breathing part of your strategy.
1:27
and they need to constantly support your cash flow and whatever your next move is. Because think about it, your loan might sit there looking exactly the
1:35
same, but literally everything around it is shifting. Lenders are constantly tweaking their assessment methods and servicing policies. And your own life,
1:43
your income, your expenses, debts, maybe you have a new dependent. All of that is changing. Add in shifting property equity, or a fixed rate expiring, and
1:52
you can see why doing nothing is a massive risk. If you’re not adjusting to these shifts, your loan becomes a trap.
1:59
When to trigger a review, because timing here is everything. Now, you often hear the standard advice, review every 6 to
2:07
12 months. But honestly, the calendar is just a baseline. If your income is super stable and you aren’t planning to buy, yeah, every 12 months is probably fine.
2:16
But if you’re actively building your portfolio, you need to be looking at this every 6 months. Planning to pull out some equity? do a review before you commit to that next project for sure.
2:26
And then there are those major life events where you just need to throw the calendar out the window. Got a pay rise?
2:31
Changing jobs? Planning for parental leave? You need to talk to a broker like yesterday. Same goes if you’re taking on a new car loan or planning a huge
2:40
renovation. These things instantly impact your lending position. So, if you’re planning parental leave, for instance, getting ahead of it means you actually understand your options before making any massive commitments. Okay.
2:51
Part three. beyond the interest rate.
2:53
Let’s get into the deeper analysis. When you work with a really good strategy focused broker, they go way deeper than just asking, “Hey, who has the lowest
3:02
rate today?” They’re looking under the hood. They’re examining your goals for the next one or two property moves.
3:07
They’re making sure your personal and investment debts are perfectly separated for tax purposes, and they really dig into your accessible equity just to make
3:15
absolutely sure your current setup isn’t going to ruin your future purchasing power. Borrowing capacity. Now, this is a highly dynamic figure. It’s not set in
3:23
stone at all. It’s this moving target that’s constantly jumping around based on bank policies and your own life changes. A broker obviously can’t
3:31
guarantee exactly what you’ll be able to borrow in 3 years, but a deep review helps you optimize the exact factors lenders use to assess you. To really
3:39
squeeze the value out of your review, there are about 10 specific questions you should be asking. Things like, does my current structure actually support my
3:46
next goal? or wait, am I paying for loan features I never even use? And critically, what are the hidden costs if we change lenders? You really can’t just
3:55
float along here. You have to make your loan work for you. Is refinancing always better? Let’s weigh the costs. So, is
4:03
refinancing your investment property always the magic bullet? No, absolutely not. Honestly, a responsible, thorough review might actually tell you to stay
4:11
exactly where you are. Please do not refinance just because some bank flashes a shiny cashback offer or a low intro rate at you. The only comparison that
4:20
matters is your overall position before and after the change. Because when you start looking at the hidden costs of switching, it’s pretty eye opening.
4:28
You’ve got discharge fees, new valuation expenses, government charges, maybe even LMI again. Or say you extend your loan
4:36
term. Sure, your monthly repayment drops, but you could end up paying a massive amount of extra total interest over the life of the loan. The lowest
4:44
advertised rate is definitely not always the cheapest option overall. And this is exactly why the distinction between a bank and a strategy focused broker is so
4:53
important. If you walk into a bank, it’s highly transactional. They’re only going to pitch you their own products. But a good broker, they see the whole board.
5:02
They understand that one single loan decision ripples through your entire portfolio. and they won’t push you to refinance if staying put is actually
5:09
your best strategic move. All right, finally, part five, preparing for your review. Preparation is basically
5:17
everything here, and it really comes down to three steps. First, get your paperwork together. Loan statements, income evidence, living expenses, credit
5:25
limits, the whole shebang. Second, actually write down the next two ideal property moves you want to make, even if they’re just tentative right now. And
5:33
third, have your specific questions ready. This gives your broker the exact ammo they need to figure out if your setup is pushing you forward or secretly
5:41
holding you back. The absolute best time to discover a finance problem is way before you actually need the money.
5:48
Setting a recurring reminder for a strategy review means you won’t be forced into rushed disastrous decisions when a great property opportunity
5:55
suddenly pops up out of nowhere. So, as we wrap up this explainer, take a second to ask yourself, are you genuinely ready to jump on your next property
6:03
opportunity without rushing? Is your finance plan truly built for what’s next? Or have you fallen into the set and forget trap? To make sure you’re
6:11
totally prepared and never caught off guard, head over to property chat.ai right now. It is a brilliant resource loaded with over 20 years of property
6:20
investing and mortgage education. Brush up on your knowledge, get those questions ready, and book that critical strategy review. Because I’ll leave you
6:27
with this one thought. If you don’t actively take control of your loan strategy today, how much wealth is your inaction going to cost you tomorrow?
Frequently Asked Questions
How long does a mortgage review take?
The initial conversation may take less than an hour, although more time can be needed for complex property portfolios. Preparing complete and accurate documents in advance will usually make the investment loan review more efficient.
Does a review affect my credit score?
A general discussion or annual mortgage review does not usually require a formal credit application. Ask your broker before authorising a credit check or submitting an application, as credit enquiries may appear on your credit file.
Should I review my loans if I am not buying again?
Yes. Your priorities may involve improving cash flow, reducing debt, reviewing loan features or preparing for retirement rather than purchasing another property. Your existing arrangements should still reflect those goals and your wider financial position.
Do I need to refinance after every annual review?
No. A mortgage strategy review is an assessment, not an obligation to switch lenders. Keeping your existing loan can be appropriate when the costs, risks, structural consequences or lost features outweigh the potential benefits.