What Makes a Good Investment Property
Key Takeaways
- Start with the location, but investigate why people want to live there and whether that demand is likely to continue.
- Choose the type of dwelling local renters and owner-occupiers already prefer.
- Look beyond gross rental yield to maintenance, vacancies, finance costs and other holding expenses.
- Favour properties with more than one realistic pathway for creating and retaining equity.
- Treat cosmetic problems differently from structural, planning or location problems.
- Use a buyer’s agent for research, execution and negotiation, not as a substitute for understanding your strategy.
- Verify prices, rents, vacancy rates, planning information and all other figures using current independent data and qualified professionals.
What makes a good investment property is not a stylish presentation, a fashionable postcode or a persuasive sales pitch. It is the combination of a well-supported location, a property that matches local demand and multiple ways to create and retain equity. For a time-poor Australian investor, that distinction matters. A house can look impressive at Saturday’s inspection and still become an expensive mistake. Before you buy, you need a repeatable framework that separates cosmetic appeal from investment fundamentals and helps you ask a buyer’s agent, building inspector, broker and conveyancer the right questions.
Whether you are researching property investment for beginners or adding to an established portfolio, the goal is the same: make a decision based on evidence, not excitement. No single number can tell you whether a property is worth buying. Strong property investment criteria consider the location, dwelling, tenant market, purchase price, ongoing costs, value-creation potential and risks together.
Why can an attractive property still be a poor investment?
A polished property can hide weak fundamentals. New paint, styled furniture and a tidy garden influence emotion, but they do not create employment, rental demand or restricted housing supply.
This is where investors often become vulnerable. After weeks of scrolling through listings and losing at auctions, a renovated kitchen can feel like evidence that a property is good. In reality, you may be paying a premium for work that has already been completed while accepting limited scope to add further value.
The more serious problems are usually less photogenic:
- Too many similar dwellings competing for tenants
- A property type that does not suit the suburb
- High strata fees or recurring maintenance costs
- Major structural or waterproofing defects
- Dependence on one local employer or industry
- Poor access to transport, schools or amenities
- A layout that discourages the dominant tenant or buyer group
- An asking price unsupported by comparable sales
- Flood, bushfire, contamination or insurance risks
- Planning restrictions that prevent your intended improvements
Paint can be changed. An oversupplied location, unsuitable floor plan or compromised position beside a major noise source is much harder to fix.
A useful rule is to separate problems into three categories:
| Type of problem | Examples | Investor response |
| Cosmetic | Paint, flooring, lighting and landscaping | Obtain quotes and test whether improvements will add sufficient value |
| Functional | Poor storage, awkward layout or limited parking | Investigate whether the problem can be corrected cost-effectively |
| Fundamental | Oversupply, major structural defects, severe noise or weak demand | Treat cautiously and be prepared to walk away |
What property investment criteria should you assess first?
If you are wondering how to evaluate an investment property, begin with five connected areas:
- Location demand: Why do people want to live in the area?
- Property fit: Does the dwelling suit local tenants and future buyers?
- Financial sustainability: Can you manage the income, expenses and periods of pressure?
- Equity potential: Can you buy well, add value or benefit from durable demand?
- Risk and exit options: Can you hold or sell the property if the original plan takes longer than expected?
These property investment criteria create a consistent process. They also stop you from changing your standards simply because a particular property has caught your attention.
How should you assess the location first?
The right location has established demand and credible reasons for that demand to continue. Historical capital growth is a useful context, but it should never be treated as a promise of future performance.
Start by investigating several indicators together rather than chasing a single hot suburb statistic:
| Location factor | What you are trying to establish |
| Vacancy trends | Whether tenants have many competing choices and whether conditions are changing |
| Rental demand | Whether comparable homes attract consistent interest |
| Population change | Who is arriving and what type of housing they require |
| Employment | Whether jobs are stable and spread across several industries |
| Infrastructure | Whether transport and services genuinely improve liveability |
| Local amenities | Whether schools, shops, parks and healthcare support demand |
| Housing supply | Whether excessive construction could weaken scarcity |
| Price position | Whether the suburb remains accessible to a broad buyer pool |
| Planning and zoning | Whether future development could help or harm the property |
| Environmental risk | Whether flooding, bushfire, contamination or insurance costs affect the asset |
The reason behind population growth matters more than the headline number. Growth driven by families creates different housing demand from growth driven by students, retirees or workers attached to a temporary project.
A diversified employment base is generally more resilient than a town dependent on one mine, factory or government department. Likewise, a transport project may improve accessibility, but it can also bring noise, disruption or new competing supply. The announcement alone is not the analysis.
If you are searching for a capital growth property, look for several independent demand drivers rather than relying on one forecast. Population, employment, infrastructure, affordability and restricted supply should form a coherent investment case.
Read How to Pick the Right Suburb for Investment Growth for a more detailed suburb research framework.
PropertyChat.ai’s property investing resources can help you organise these established research principles. However, the platform does not provide live suburb data, current prices or up-to-date growth forecasts. Check present-day evidence through reliable data providers, government sources and qualified local professionals before acting.
What type of property fits local demand?
The safer choice is usually a property that resembles what the area’s renters and future buyers already want. You are not buying for your personal taste. You are buying an asset for a defined local market.
If most households seeking homes in a family suburb want three bedrooms, a usable backyard and access to schools, a compact one-bedroom apartment may have a narrower audience. Conversely, a large house with extensive gardens may be poorly matched to a location dominated by students and young professionals.
Match the dwelling to the dominant demographic
Consider how the likely occupant actually lives:
- Families often value bedrooms, storage, schools, parks, parking and secure outdoor areas.
- Young professionals may prioritise transport, employment centres, cafés and low-maintenance living.
- Students generally seek affordability, practical layouts and access to education or public transport.
- Downsizers may prefer single-level access, manageable outdoor space, security and nearby services.
This demand matching reduces your reliance on finding an unusual tenant or buyer later. It may also reduce vacancy and protect resale appeal.
Before engaging a buyer’s agent, define your preferred dwelling, tenant profile, risk limits and value-creation strategy. Otherwise, you risk outsourcing the search without retaining control of the decision.
What should you look for in an investment property?
When inspecting a shortlisted property, focus on practical features that support tenant demand, owner-occupier appeal and manageable ownership.
Look for:
- A functional floor plan without wasted or unusable spaces
- Bedrooms of a practical size
- Natural light and ventilation
- Appropriate heating and cooling
- Useful storage
- Parking where the local market expects it
- Low-maintenance outdoor areas
- A street position that supports safety and liveability
- Reasonable access to transport, schools, shops and employment
- A building condition that matches your budget and experience
- Features that can be improved without overcapitalising
Also examine what cannot easily be changed. A poor street position, serious aircraft noise, an unsuitable building orientation or a problematic neighbouring use may permanently restrict demand.
How do rental yield and cash flow affect the decision?
Rental yield helps you compare rent with the purchase price, but it is only an initial filter.
Gross rental yield is commonly calculated as:
Annual rent ÷ purchase price × 100
A property receiving
500 per-weeks
500perweekearns26,000 in gross annual rent. If purchased for $500,000, its gross rental yield is 5.2 per cent. That does not mean the investor receives a 5.2 per cent return.
The property may also carry:
- Council and water charges
- Insurance
- Property management fees
- Repairs and maintenance
- Strata or body corporate costs
- Land tax where applicable
- Vacancy periods
- Advertising and reletting expenses
- Loan interest and finance costs
- Future capital works
A high advertised yield can quickly lose its appeal if the property has expensive defects, unreliable demand or heavy ongoing costs. Equally, a lower-yielding property may not suit your serviceability or holding capacity, even if its long-term prospects appear attractive.
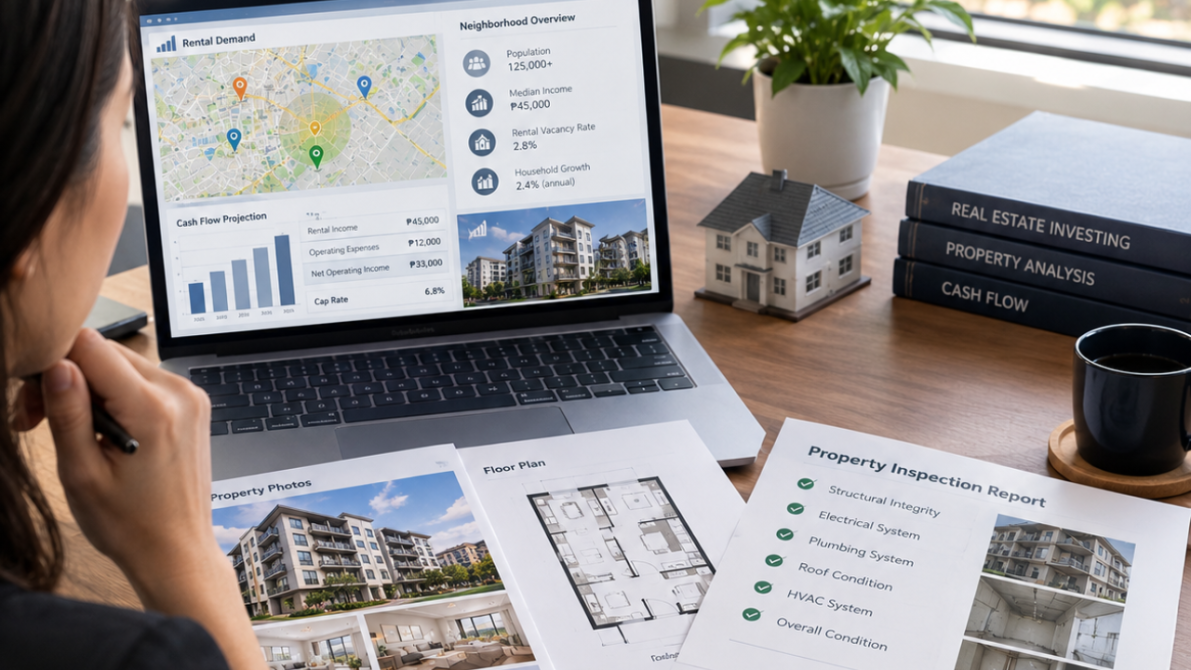
Gross rental yield, net yield and cash flow
These measurements answer different questions:
| Metric | What it shows |
| Gross rental yield | Rent as a percentage of purchase price before expenses |
| Net rental yield | Property income after eligible operating expenses |
| Cash flow | The actual surplus or shortfall after income, expenses and finance commitments |
| Return on investment | The return relative to the money you have contributed |
| Capitalisation rate | Net operating income relative to the property’s value, generally before finance costs |
Some investors encounter the term cap rate real estate when reading international property material. A capitalisation rate can be useful, particularly when comparing income-producing assets, but Australian residential investors more commonly discuss gross rental yield, net yield and cash flow. Whatever metric you use, apply the same calculation method to every property.
The best decision is not automatically the property with the highest yield. It is the property whose income, expenses, risks and strategy fit your financial position.
A positive cash flow property may provide an income surplus after expenses, but positive cash flow alone does not guarantee strong capital growth or low risk. Likewise, a property with a short-term cash flow shortfall may still suit some investors, but only if the holding costs are affordable and the wider investment case is supported by evidence.
The return on investment property owners ultimately achieve can be influenced by rent, vacancies, finance costs, transaction costs, tax, maintenance, improvements and changes in value. Avoid reducing that complex outcome to one advertised percentage.
Read Sustainable Rental Income for a detailed explanation of tenant demand, vacancy, expenses and cash flow stress-testing.
Have a licensed financial adviser, accountant and mortgage professional assess the implications for you. PropertyChat.ai offers education based on more than 20 years of investing, renovation and mortgage experience, but it does not calculate investment returns or provide personal financial advice.
Should you prioritise rental yield or capital growth?
The rental yield vs capital growth decision should reflect your strategy, income, borrowing position, timeframe and capacity to hold the property.
A property focused on rental income may help support cash flow but still have weaker long-term demand or limited resale appeal. A growth-oriented property may offer stronger underlying demand but place more pressure on your household budget.
Rather than asking which one is universally better, ask:
- How much shortfall can I comfortably manage?
- What happens if the property is vacant?
- Can I afford higher repayments or major repairs?
- What evidence supports future buyer and tenant demand?
- Does the property offer another way to create equity?
- How long can I hold the property if growth is slower than expected?
The aim is not to find a perfect property. It is to find a well-supported property that fits your plan without exposing you to risks you cannot manage.
How can a property provide multiple ways to build equity?
A strong investment gives you more than one possible way to make progress. This is the logic behind the Trident strategy described in the PropertyChat.ai knowledge base:
- Buy well.
- Add value.
- Hold in a location supported by long-term demand.
Buying below fair market value can create an initial equity buffer, provided recent comparable sales genuinely support the valuation. For example, if reliable evidence indicates a property is worth around
400,000 and you secure it for
400,000 and you secure it for 350,000 due to a motivated sale, the difference may provide a valuable starting position.
It is not guaranteed profit. Stamp duty, legal expenses, finance costs, inspection fees, repairs and future market movement still matter.
A well-planned renovation may then improve the property’s appeal, rent or valuation. Development, subdivision or additional floor space could offer other pathways, but each brings planning, construction and financial risk.
Before proceeding, establish:
- The current value using comparable sales
- The complete cost of the proposed work
- A realistic contingency
- Holding and finance costs during the project
- Whether council or strata approval is required
- The likely completed value
- The likely rental increase
- Whether local buyers and tenants value the proposed changes
Explore the renovation education hub before assuming every tired property is an opportunity. The most profitable-looking project can become the most dangerous if the budget ignores approvals, hidden defects, holding costs or overcapitalisation.
Why do scarcity and owner-occupier appeal matter?
Scarcity can help protect desirability. A character home in an established suburb with restricted new development may face less direct competition than a standard apartment in an area with thousands of similar units planned.
Scarcity alone is not enough. The dwelling still needs to be useful, affordable to its target market and positioned where people want to live.
Owner-occupier appeal is also important because emotional buyers may compete for homes that provide lifestyle, comfort and a sense of belonging. Features such as natural light, practical bedrooms, storage, outdoor space and an appealing street can broaden future demand.
The goal is not to create something eccentric. It is to improve or preserve the features the local market already values.
Ask three questions:
- How easily can another property like this be supplied?
- Does the property appeal to both tenants and owner-occupiers?
- Will the property remain useful if local preferences change?
What should a buyer’s agent contribute?
A capable buyer’s agent should turn your strategy into a disciplined search. Their role can include sourcing properties, analysing comparable sales, inspecting homes, identifying risks and negotiating with selling agents.
Ask prospective buyer’s agents:
- Do you represent only buyers?
- How are you paid?
- Do you receive referral fees or commissions?
- What evidence supports the suburb and property recommendation?
- How do you assess competing supply and local demographics?
- What comparable sales support the proposed price?
- How do you evaluate renovation or development potential?
- Which risks would make you recommend walking away?
- How will you document the investment case?
- What services are excluded from your fee?
A buyer’s agent can save time, but expertise should create transparency rather than dependence. You should understand why a property meets your criteria, not merely be told that it does.
For further guidance, read Buyer’s Agent for Investment Property: When It Makes Sense and When It Doesn’t.
What belongs on your investment property due diligence checklist?
Before making an unconditional commitment, assess the opportunity across five areas.
Location
- Demand drivers are genuine, established and diversified.
- Vacancy and rental evidence have been checked using current sources.
- The street position supports liveability and future resale.
- Future housing supply and planning changes have been investigated.
- Environmental, insurance and noise risks have been reviewed.
- Infrastructure claims have been verified through government or council sources.
Property
- The dwelling suits the dominant demographic.
- Building and pest inspections identify no unacceptable defects.
- The layout is functional.
- Maintenance requirements are manageable.
- Strata records have been reviewed where applicable.
- Proposed improvements are practical and permitted.
Numbers
- Recent comparable sales support the price.
- Rent has been assessed conservatively using comparable leased properties.
- All ownership and improvement costs are included.
- Vacancy and maintenance allowances have been included.
- Finance has been reviewed by an appropriate professional.
- Cash flow has been stress-tested against less favourable conditions.
Equity potential
- Proposed improvements meet proven local preferences.
- Renovation costs include contingencies.
- Planning or zoning potential has been verified with the council and relevant specialists.
- The finished value is supported by comparable evidence.
- The expected value increase exceeds the complete project cost by a sufficient margin.
Exit options
- The property appeals to more than one narrow buyer group.
- It can be rented without relying on unusual conditions.
- You understand how the investment performs if renovation or growth takes longer than expected.
- You have a financial buffer for vacancies, repairs and higher finance costs.
- You can explain what would cause you to sell, hold or change strategy.
For a structured comparison process, read How to Compare Investment Properties. For established guidance on larger projects, the property development resources provide another useful educational starting point.
What are the biggest investment property warning signs?
Not every weakness means you should reject a property, but some problems deserve serious caution.
Warning signs include:
- A price that cannot be supported by comparable sales
- Dependence on optimistic rent or growth assumptions
- High vacancy or rapidly increasing rental supply
- A property type that does not match local households
- Major defects without a detailed repair scope
- Unusually high strata fees or planned special levies
- Heavy reliance on one employer or temporary project
- Proposed infrastructure being presented as guaranteed
- Renovation plans that depend on unconfirmed approvals
- Little difference between unrenovated and renovated values
- A narrow resale market
- Cash flow that fails under a modest stress test
- Pressure to buy before completing due diligence
A strong investment case should become clearer as you investigate it. If every concern requires another optimistic assumption, the property may not offer an acceptable margin of safety.
A worthwhile property is rarely identified by one exciting number. It earns its place in your portfolio by combining a well-supported location, a locally appropriate dwelling, manageable holding demands, limited competing supply and several realistic pathways for equity creation.
The question is not simply, “Is property a good investment?” The more useful question is, “Does this particular property suit my strategy, finances and risk limits, and is the investment case supported by current evidence?”
Use the property investment criteria in this guide to assess the location, dwelling, numbers, equity potential and exit options consistently. That process will not remove every uncertainty, but it can help you avoid making a major financial decision based on styling, sales pressure or one attractive statistic.
This framework draws on PropertyChat.ai, together with Jane Slack-Smith’s more than 20 years of property investing, mortgage and renovation education. It provides a foundation for asking better questions, not a replacement for current research or professional advice.
Before your next inspection, visit PropertyChat.ai and ask: “What should I investigate before buying this type of investment property?” Use the response to organise your due diligence, then take your findings to your buyer’s agent, broker, conveyancer, building inspector, accountant and other qualified advisers for property-specific verification.
Suggested PropertyChat.ai articles
- How to Compare Investment Properties
- How to Pick the Right Suburb for Investment Growth
- Sustainable Rental Income
- What Makes an Investment Property Future-Proof?
- How to Minimise Investment Risk in a Volatile Market
- How Holding Costs Differ Between Houses, Apartments and Townhouses
This article is provided in line with the Brand Voice of PropertyChat and Your Property Success, emphasising trust, actionable advice, and long-term partnership in property finance.
Transcript
Good Investment Properties: How to Spot Real Estate Worth Buying
0:00
Welcome to this explainer. Today we’re tackling a massive question. What makes a property actually worth buying from an investment perspective? Let’s be honest,
0:08
it’s so easy to walk into a Saturday open house, smell that fresh paint and brewed coffee, and completely fall in love. But buying purely on emotion,
0:17
well, that’s how time poor buyers end up making incredibly expensive mistakes.
0:22
Our goal today is to help you build wealth methodically instead.
0:26
So, you might be wondering, why can a gorgeous, highly attractive property still be a terrible investment? Picture this. You’ve been scrolling listings for
0:34
weeks, maybe getting outbid, and suddenly, boom, you see it. A beautifully staged house with a stunningly renovated kitchen. It feels
0:42
like a total win, right? But here’s the catch. That polished surface can completely blind us to weak, unchangeable fundamentals. Sure, a nice
0:51
aesthetic plays on our emotions, but cosmetics do absolutely nothing to create local jobs. They don’t drive real demand, and they definitely do not
0:59
restrict housing supply. To get us out of that emotional trap, we’ve got a really structured agenda. Today, we’re going to cover the cosmetic trap, the
1:07
five core investment criteria, matching dwellings to demographics, yield versus risk, and finally, the Trident equity
1:14
strategy. Let’s kick things off with section one, the cosmetic trap, and how to avoid those superficial buying habits. As an investor, you’ve got to be
1:23
absolutely ruthless about how you categorize a property’s problems. If a place has ugly paint, dated flooring, or just terrible landscaping, look, that’s
1:31
merely a cosmetic issue. Your move is simple. Get some quotes and see if fixing it actually adds value. Now, if it’s got zero storage or a really weird,
1:40
awkward layout, that’s functional. You need to dig in and figure out if it can be fixed cost- effectively. But if you’re staring down an overs supplied
1:48
market, major structural defects, or just dead local demand, those are fundamental disasters. Treat those with extreme caution. And honestly, be totally prepared to just walk away.
2:00
There’s a great saying that sums this up perfectly. Paint can be changed, but an overs supplied location, a terrible floor plan, or being right next to a noisy highway is much harder to fix.
2:10
Paying top dollar for a trendy kitchen is incredibly dangerous if the house backs onto a loud, busy road. You’re literally paying a premium for cosmetics
2:19
while taking on a permanent flaw that’s going to cap your demand forever. The five core investment criteria, otherwise known as the master builder framework.
2:28
If we’re actively ignoring the shiny cosmetics, what should we actually be looking for? Well, you need to build your investment on these five core
2:35
steps. Step one is location demand. Why do people actually want to live here?
2:40
Step two is property fit. Does this specific house actually suit the locals? Step three, financial sustainability.
2:47
Can you handle the holding costs when things get tight? Step four is equity potential. Are there realistic ways to force the value up? And finally, step
2:56
five, risk and exit options. Can you pivot if things go south? Sticking to this repeatable framework stops you from lowering your standards just cuz a house
3:04
looks pretty. matching dwellings to demographics where we focus on concrete fundamentals over cosmetics. Now, this
3:11
part requires a massive mindset shift for a lot of folks. You’ve got to step completely out of that owner occupier mentality. Listen closely. You are
3:20
absolutely not buying for your own personal taste. You’ve got to stop projecting your own lifestyle onto the asset. You are buying a financial
3:28
vehicle for a very strictly defined local market. Let’s look at a side-by-side comparison because it perfectly highlights why this matters.
3:37
If a suburb is driven by families, what do they want? They want three bedrooms, usable backyards, and good school access. Trying to rent out a slick,
3:45
compact one-bedroom apartment in that neighborhood is literally like trying to sell a two-seater sports car to a family looking for a minivan. It just won’t work, no matter how spectacular it
3:54
looks. On the flip side, if you’re buying in a hub for students or young professionals who want transport and cafes, a massive house with high
4:01
maintenance gardens is a terrible mismatch. You just got to buy exactly what the local market already demands.
4:07
All right, let’s talk money in section 4. Yield, cash flow, and risk, or as I like to call it, the illusion of yield.
4:16
So, you’re scrolling and you see a listing bragging about a strong gross rental yield, maybe something like 5.2%.
4:22
It’s a really comforting, simple calculation, right? Just divide the annual rent by the purchase price. Say 500 bucks a week in rent on a $500,000
4:30
property. Boom, 5.2%. It’s so easy to see that number and excitedly assume this property is just going to effortlessly pay for itself.
4:39
But hold on a second, cuz that gross yield is totally a mirage once we step into the real world. You definitely do not get to keep that 5.2%.
4:48
First, you’ve got to subtract council and water charges, plus insurance and property management fees. Got strata or body corporate costs? Add those in.
4:56
Then, you’ve got to factor in vacancy periods, advertising, loan interest, and inevitably future maintenance. All of these hidden expenses aggressively eat
5:04
away at your actual cash flow. That high advertised yield loses its appeal really fast if the property carries expensive
5:11
defects. With the income risks mapped out, let’s jump into section five, the Trident Equity Strategy, which is all about building wealth systematically.
5:20
You know, a truly strong investment doesn’t just rely on hope. You don’t just buy a place, cross your fingers, and pray the market goes up. You need
5:28
multiple realistic pathways to create equity. First, you’ve got to buy well, meaning below fair market value backed by real comparable sales, which gives
5:36
you an instant equity buffer. Second, you add value through smart improvements that the local market actually wants.
5:42
And third, you hold. You hold that property in a location supported by durable, diversified demand. And a massive part of that hold step relies on
5:51
one absolutely crucial concept, scarcity. You want a property with features that restrict competing supply.
5:58
Think about it. A beautiful character home in an established suburb with strict zoning laws faces way less competition than some cookie cutter
6:06
apartment in an area where the council is about to approve thousands of identical units. Scarcity protects your property’s desiraability, and that is
6:13
exactly what protects your long-term capital growth. Finally, let’s wrap things up with warning signs and next steps to empower your investment
6:21
journey. Before you even think about signing a contract, you need a strict system for spotting red flags. Treat these warning signs as absolute
6:28
dealbreakers. Price isn’t supported by comparable sales data, walk away. Cash flow collapses if interest rates bump up or if you face a short vacancy, walk
6:37
away. If the property type doesn’t match local demographics or if the whole town relies on just one major employer, that’s a massive risk. A solid
6:46
investment case gets clearer the deeper you dig. If every single concern requires you to make some wildly optimistic assumption, the property just
6:54
doesn’t offer an acceptable margin of safety. So, I want you to ask yourself this vital question every single time you feel that emotional urge to bid on a
7:03
beautiful but potentially flawed property. Does this particular property suit my strategy, my finances, and my
7:11
risk limits? And is the investment case supported by current evidence? It’s all about shifting your focus from aesthetic appeal to rigorous hard-nosed
7:19
validation. To turn this entire master builder framework into action, you really need to structure your due diligence. Head over to property chat.ai
7:29
right now to organize your research and get the exact questions you need to ask before you step foot in your next openhouse. Again, that’s property
7:36
chat.ai. Because at the end of the day, you have to ask yourself, are you buying a property just to look rich on a Saturday afternoon, or are you buying
7:44
one to actually be rich a decade from now? Think about it.
Frequently Asked Questions
Is a high rental yield enough to make a property worth buying?
No. A high rental yield may be offset by vacancies, repairs, strata fees, weak growth drivers, unreliable tenant demand or limited resale appeal. It may also reflect risks the market has already priced into the property.
Assess gross and net rental yield, cash flow, property condition, holding costs, local demand and future supply together. A slightly lower yield may be more sustainable if the property attracts a broad tenant pool and has manageable ongoing costs.
Should I buy a house or a unit as an investment?
Choose the dwelling type that matches local demand and your budget, holding capacity and strategy. A suitable unit can outperform an unsuitable house, and vice versa.
Investigate land component, strata fees, maintenance, competing supply, tenant demand and owner-occupier appeal. Compare the property with similar dwellings rather than relying on broad assumptions that one property type is always better.
Is buying below market value always possible?
No. Genuine discounts require evidence from recent comparable sales, the property’s condition and the circumstances of the sale. A lower asking price does not automatically represent value if the property has defects, weak demand or substantial future costs.
Calculate the complete acquisition and repair cost before deciding that a property is undervalued. An independent valuation and appropriately qualified professionals may help you verify your assumptions.
Can PropertyChat.ai tell me which suburb to buy in now?
No. PropertyChat.ai provides general education based on more than 20 years of established property investing, renovation and mortgage knowledge. It does not supply live market data, current suburb recommendations, projected return calculations or personal financial advice.
Use PropertyChat.ai to structure your research and identify useful due diligence questions. Always verify current prices, rents, vacancy rates, planning information and other figures independently before making an investment decision.